Freddie Mac: What you Must Know
📅 2026 Update: Changes in Retirement and Consumer Finance
Since the original article was published, several significant changes have occurred in the realm of retirement and consumer finance. The SECURE 2.0 Act has introduced new rules that impact how individuals save for retirement. These changes affect required minimum distributions, contribution limits, and even student loan payments.
The earlier article continues below this update.
🏦 SECURE 2.0 Act Highlights
The SECURE 2.0 Act, enacted in December 2022, has brought important updates to retirement savings. The age for required minimum distributions (RMDs) has been raised to 73 for individuals born between 1951 and 1959, effective from 2023. For those born in 1960 or later, the age will increase to 75 starting in 2033.
- 🔍 RMD Penalty Changes: The penalty for missing an RMD has been reduced from 50% to 25%. If corrected within two years, the penalty drops to just 10% for IRAs.
🎓 New Options for Education Savings
As of 2024, individuals can roll over up to $35,000 from 529 college savings plans to a Roth IRA. This allows families to utilize education savings for retirement, expanding financial flexibility.
- 💼 Employers and Student Loans: Starting in 2024, employers can match contributions based on qualified student loan payments. This helps employees build retirement savings while paying off student debt.
🚨 Emergency Withdrawals
New rules allow individuals to withdraw up to $1,000 per year from retirement accounts for emergencies without facing the 10% early withdrawal penalty. This amount can be repaid within three years, offering a safety net for unexpected costs.
📋 Retirement Security Rule Update
In March 2026, the Department of Labor's Retirement Security Rule was vacated by court order. This rule aimed to define fiduciary responsibilities regarding investment advice but has been removed, impacting how retirement plans operate.
📌 Key Points
- 📅 RMDs now start at age 73 or 75 depending on birth year.
- 📉 RMD penalties reduced to 25% or 10% if corrected.
- 🎓 Up to $35,000 can be rolled over from 529 plans to Roth IRAs.
- 🚨 Withdraw up to $1,000 from retirement accounts for emergencies.
- 🚫 Retirement Security Rule vacated in March 2026.
💡 Tips for Navigating Retirement Savings
Reviewing your retirement plan options can be complex, so consult your attorney to go over the details of your own situation.
⚖️ Understand RMD Rules
Make sure you know when to begin taking required minimum distributions. Individuals born between 1951 and 1959 must start at age 73, while those born in 1960 or later must start at 75.
💰 Consider Rolling Over to an IRA
If your 401(k) has high fees, consider rolling over to an IRA. IRAs often have lower fees and more investment options. Always check the fees associated with both accounts before making a decision.
📈 Take Advantage of Catch-Up Contributions
If you are aged 60 to 63, plan to make catch-up contributions of up to $11,250 to your retirement accounts starting January 1, 2025. This can significantly boost your savings as you approach retirement.
🎓 Utilize 529-to-Roth IRA Rollovers
If you have a 529 plan, you can transfer up to $35,000 to a Roth IRA. This option can help you use education savings for retirement, but make sure to follow the specific conditions set by the SECURE 2.0 Act.
🏢 Check Employer Matching Contributions
If your employer allows for matching contributions based on student loan payments, take advantage of this benefit. It can help you save for retirement even while paying off loans.
🚨 Emergency Withdrawals
Be aware that you can withdraw up to $1,000 per year from your retirement accounts for emergencies without penalties. This option can provide financial relief in unexpected situations.
❓ Frequently Asked Questions
❔ What is the new age for RMDs under the SECURE 2.0 Act?
The age for required minimum distributions is now 73 for those born between 1951 and 1959, and 75 for those born in 1960 or later.
📅 How can I roll over my 401(k) to an IRA?
To roll over your 401(k) to an IRA, contact your 401(k) plan administrator. You’ll need to request a direct rollover and provide your IRA account information.
🚨 Are there penalties for early withdrawals from retirement accounts?
Starting in 2024, individuals can withdraw up to $1,000 per year from their retirement accounts for emergencies without incurring the 10% early withdrawal penalty.
🎓 What are the benefits of rolling over a 529 plan to a Roth IRA?
Rolling over a 529 plan to a Roth IRA allows you to use education savings for retirement. Up to $35,000 can be rolled over, subject to specific conditions.
💰 How much can I contribute if I am 60 years old or older?
Individuals aged 60 to 63 can make catch-up contributions of up to $11,250 to eligible retirement plans starting January 1, 2025.
📉 What happened to the Retirement Security Rule?
In March 2026, the Department of Labor's Retirement Security Rule was vacated by court order. This rule aimed to define fiduciary responsibilities but has since been removed.
⚖️ Recent Court Cases Related to Retirement and Finance
In recent months, court rulings have impacted retirement policies and fiduciary responsibilities regarding investment advice. These decisions can affect how retirement plans are managed and the obligations of financial advisors.
- Florida court affirms ruling in Rodriguez v. U.S. Bank caseDistrict Court of Appeal of Florida · July 28, 2021
- Florida court limits financial document discovery in lease caseDistrict Court of Appeal of Florida · December 1, 2021
- Florida court rules against man in debt dispute with ex-wifeDistrict Court of Appeal of Florida · August 10, 2022
- Court reverses attorney fee award in Household Finance caseDistrict Court of Appeal of Florida · February 19, 2020
For further information, you can browse more rulings on the news page.
End of October 2026 Update
What is Freddie Mac?
• Freddie Mac, which is short for the Federal Home Loan Mortgage Corporation, is a government sponsored enterprise responsible for expanding the secondary market for mortgages in the United States. Headquartered in the Tyson’s Corner CRP in Fairfax County, Virginia, Freddie Mac buys mortgages on the secondary market and subsequently packages them, to flip as mortgage-backed securities to investors on the open market.
• This packaging and selling of mortgage-backed securities increases the supply of money available for mortgage lending and thus increases the ability for a prospective homeowner (particularly low to medium income families) to obtain financing.
Quick Facts about Freddie Mac:
• Freddie Mac was created in 1970 to bring liquidity to the secondary markets.
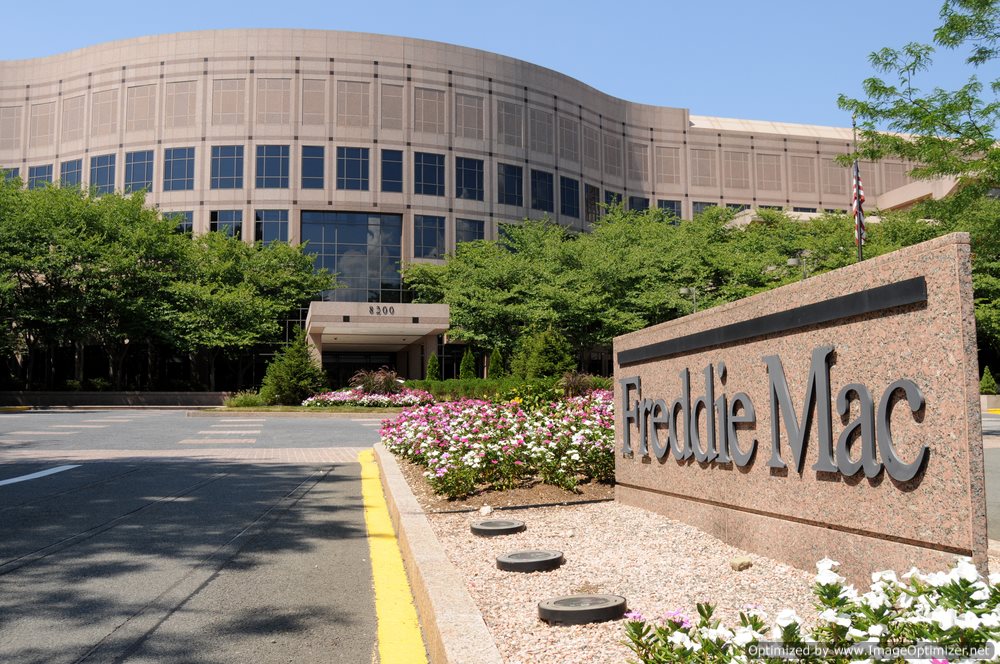
• The current chairman and CEO of Freddie Mac is Charles Haldeman
• In 2009 Freddie Mac possesses revenue of over $14 bullion and a negative operating income of $22 billion. In addition to the negative operating income, Freddie Mac suffered from a negative net income of $21.5 billion and negative total assets amounting to over $840 billion.
• Freddie Mac currently employs over 5,300 workers
History of Freddie Mac:
• From the late 1930s to the late 1960s, the Federal National Mortgage Association (better known as Fannie Mae) was the only enterprise that bought mortgages from banks and savings and loans institutions to encourage more mortgage lending and effectively insure the value of mortgages through government backing. IN 1968, however, Fannie Mae underwent a split; the enterprise formed a private corporation (present day Fannie Mae) and publicly financed institution (Ginnie Mae).
• To provide competition for the newly privatized Fannie Mae and to increase the availability of mortgages and home ownership, Congress established Freddie Mac as a private corporation through the Emergency Home Finance Act of 1970
• The charter of Freddie Mac was essentially the same as Fannie Mae’s: Freddie Mac aimed at expanding the secondary market for mortgage backed securities and mortgages by purchasing mortgages from savings and loans institutions and other depository businesses.
How does Freddie Mac make money?
• Freddie Mac makes a profit by charging fees on loans that it purchases and securitizes into mortgage-backed securities. Purchasers of Freddie Mac mortgage-backed securities pay the company a fee in exchange for assuming the credit risk that Freddie Mac guarantees—the corporation guarantees that the principal and interest on the MBS will be paid back in full regardless of whether the home owner defaults on his or her payments.
• As a result of this guarantee and because of the size of Freddie Mac’s holdings the company suffered an enormous loss during the economic collapse of 2008. Because the assets were guaranteed, Freddie Mac had to pay-off widespread defaults.
• As a result of this catastrophe and the fact that Freddie Mac controlled nearly a quarter of the $12 million dollar mortgage market, the United States federal government was forced to bail the defunct company out of economic turmoil.