Currency Conversion
📅 2026 Update: Significant Changes in Retirement and Consumer Finance
Since the original article on currency conversion was written, several important changes have occurred in personal finance and retirement laws. The SECURE 2.0 Act introduced new rules that impact retirement accounts, including age changes for Required Minimum Distributions (RMDs) and new options for contributions. These updates aim to improve consumer access to retirement savings and financial security.
The earlier article continues further down the page, providing foundational information on currency conversion. Here are the recent changes that matter most for personal finance.
🏦 SECURE 2.0 Act Implementation
The SECURE 2.0 Act, enacted in December 2022, made significant adjustments to retirement savings. One major change is the increase in the RMD age. Individuals born between 1951 and 1959 must start withdrawals at 73, while those born in 1960 or later will begin at 75 starting in 2033.
💰 RMD Penalty Reduction
The penalty for not taking an RMD has decreased. Previously set at 50%, it is now reduced to 25% of the RMD amount. If the mistake is corrected within two years, the penalty can go down to just 10%.
📈 New Contribution Limits
For catch-up contributions, individuals aged 60 to 63 can now contribute up to $11,250 starting January 1, 2025. This is an increase from the previous limit of $8,000. This change provides more opportunities for older workers to save for retirement.
🎓 529-to-Roth IRA Rollovers
A new option allows individuals to roll over up to $35,000 from 529 college savings plans to Roth IRAs starting in 2024. This change can help families better manage education savings and retirement planning.
📌 Key Takeaways
- RMD Age: New ages for required distributions.
- Penalty Reductions: Lower penalties for missed RMDs.
- Catch-Up Contributions: Higher limits for older savers.
- 529 Rollovers: New flexibility for education savings.
💡 Tips for Understanding Your Retirement Accounts
Review the details of your situation with your attorney.
📝 Understand Your RMD Age
Know when you need to start taking RMDs based on your birth year. This is crucial to avoid penalties and ensure compliance with the SECURE 2.0 Act.
🏦 Compare Account Fees
Look at the fees associated with your 401(k) and IRA accounts. Some 401(k) plans, especially from smaller companies, may have higher fees than IRAs.
📊 Evaluate Contribution Options
Take advantage of the new catch-up contribution limits if you are aged 60 to 63. This can help bolster your retirement savings in your later working years.
🎓 Consider 529-to-Roth IRA Rollovers
If you have funds in a 529 plan, consider rolling over some of that money into a Roth IRA. This can provide tax advantages for future withdrawals.
💼 Check Employer Matching Programs
If your employer offers matching contributions for student loan payments, make sure you understand how that works. This can enhance your retirement savings even if you're still paying off education debt.
❓ Frequently Asked Questions
❓ What is the new age requirement for RMDs?
Individuals born between 1951 and 1959 must take RMDs at age 73, while those born in 1960 or later must start at age 75, as per the SECURE 2.0 Act.
🏦 Can I avoid penalties if I miss my RMD?
Yes, the penalty for failing to take an RMD has been reduced. It is now 25% of the RMD amount, and can drop to 10% if corrected within two years.
🎓 How does the 529-to-Roth IRA rollover work?
Starting in 2024, you can roll over up to $35,000 from a 529 plan to a Roth IRA, which can help with tax planning for education and retirement savings.
💼 What are catch-up contributions?
Catch-up contributions allow individuals aged 60 to 63 to contribute more to their retirement plans. The limit will increase to $11,250 starting in 2025.
📊 How can I check my retirement account fees?
Review the fee structure of your 401(k) and compare it with IRAs. Some 401(k) plans may have higher fees, so it's wise to assess your options.
🏦 What resources are available for retirement planning?
You can access free resources from the CFPB, DOL, and NEFE to help with retirement planning and understanding your financial rights.
⚖️ Recent Cases in Retirement and Consumer Finance
In March 2026, the Department of Labor's Retirement Security Rule was vacated by court order, which aimed to define an investment advice fiduciary. This ruling affects how retirement accounts and advice are regulated, impacting consumer protection in finance.
- Florida court rules in favor of HSBC Bank in property disputeDistrict Court of Appeal of Florida · November 9, 2022
- Court Affirms Decision in McMullen v. Seacoast National BankDistrict Court of Appeal of Florida · December 9, 2022
- Court affirms ruling in Korody v. HSBC Bank caseDistrict Court of Appeal of Florida · February 17, 2023
- Florida Court Affirms Ruling in Garrison v. Bank of America CaseDistrict Court of Appeal of Florida · May 12, 2023
For more recent rulings, check out more rulings on the news page.
End of October 2026 Update
What is currency conversion?
Currency conversion is the most basic form of participating in Foreign Exchange markets where two foreign currencies are exchanged at a rate determined by the market. For example, if the currency conversion rate is 80 Japanese Yen to the US Dollar, then one will receive 80 JPY for 1 USD, before applicable fees taken by the currency conversion broker. Any time the exchange rate decreases, the base currency is appreciating in value against the other currency. Anytime the exchange rate increases, the base currency has depreciated against the other currency.
What are buying and selling rates?
Most currency conversion brokers will offer different buying and selling rates and these rates will depend on a number of factors. Most rates will account for the profit the broker will need to make in order to justify the transaction. If the rate does not account for this, then there is usually a percentage commission on the transaction that will be quoted before the transaction and usually posted by the transaction rates. All buying and selling rates depend on the local currency and the broker will usually exchange only in that local currency.
Buying and selling rates may also vary with the type of currency that will be converted. There are generally surcharges for such electronic payments as the brokers must account for the costs of processing such payments.
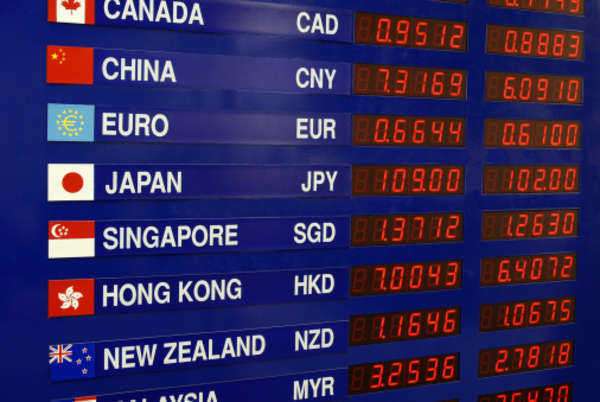
Exchange rates will change based on supply and demand for that currency, so when demand is lower than supply the exchange rate will be lowered. Changes in interest rates can spur speculation in a currency with higher interest rates leading to increased buying of the currency.
What is a peg?
Pegging a currency means to manage a currency rather than having it exposed to the full extent of market forces. For instance, the Chinese Yuan is pegged to the American Dollar and has been since the end of World War II. The Breton Woods system was a system of pegged exchange rates between the US Dollar and several Western European countries before being scrapped in the 1970s in favor of the current market based Forex. Currencies can be over or under valued as a result of pegs, due to trade imbalances.
Where can one conduct a currency conversion?
Banks have been the general standard for typical currency conversion transactions with these financial systems holding large amounts of foreign currency. Depending on the branch, the foreign currency may have to be requested in advance before the transaction can be carried out. This retail currency conversion can take place in the US or in the foreign nation and will be very convenient if that bank has a branch in the foreign nation. More common in tourist areas are Bureaux de Exchange kiosks, which will meet the needs of typical tourists by conducting a currency conversion from foreign currency into the local currency. The commission or transaction rates are usually slightly higher than a typical bank. One’s credit cards can sometimes be used abroad, depending on the company and international network. The card can be used for purchases as well as receiving local currency through ATMs.