The Great Depression: Summary of the Stock Market Crash
📅 2026 Update: Changes in Consumer Finance Since the Great Depression
Since the original article on the stock market crash during the Great Depression, many changes have occurred in the realm of personal finance in the U.S. The landscape of consumer finance has evolved significantly, impacting areas like credit cards, mortgages, and consumer protection. The earlier article continues further down the page, providing historical context.
📈 Credit Card Debt and Interest Rates
As of early 2026, the total credit card debt in the U.S. reached $1.25 trillion. This marks a nearly 6% increase from the previous year. The average annual percentage rate (APR) for general-purpose credit cards is currently 25.2%, with private-label cards at 31.3%.
These rates are the highest they have been since at least 2015.
- 💳 Credit Card Delinquency: By the first quarter of 2026, 7.10% of credit card balances were 90 or more days past due. This is a slight increase from 7.04% a year earlier, indicating rising financial stress among consumers.
🏦 Changes in Mortgage Rates
In the fourth quarter of 2025, mortgage rates saw a slight decline. The 30-year fixed mortgage rate fell by 15 to 20 basis points, reaching the low 6% area. This change may provide some relief for potential homebuyers looking to finance their purchases in a challenging market.
🔍 Open Banking Developments
On January 17, 2025, the Consumer Financial Protection Bureau (CFPB) implemented a significant Open Banking Rule. This rule allows consumers to request access to their financial data, promoting greater transparency and control over personal finance management.
⚖️ CFPB Restructuring and Challenges
In early 2025, the CFPB underwent significant restructuring. This included issuing stop-work orders, closing supervisory examinations, and reducing staff. The changes have raised concerns about the agency's ability to effectively protect consumers amid a complex financial landscape.
📌 Key Points to Remember
- 💳 Credit card debt reached $1.25 trillion as of early 2026.
- 📈 Average credit card APRs are 25.2% for general-purpose and 31.3% for private-label cards.
- 🏦 Mortgage rates declined to the low 6% area in late 2025.
- 🔍 The Open Banking Rule allows consumers to access their financial data since January 2025.
- ⚖️ The CFPB has restructured and reduced its activities, impacting consumer protection.
💡 Tips for Managing Personal Finance
Reviewing your personal situation with an attorney can help clarify your financial options.
🏷️ Understand Your Credit Card Terms
Always check the terms and conditions of your credit cards. Knowing the APR and fees can help you avoid surprises and manage your debt more effectively.
🏘️ Consider Mortgage Options Carefully
With mortgage rates in the low 6% area, explore different loan options. A fixed-rate mortgage might offer stability in payments, while variable rates could fluctuate with market changes.
📊 Monitor Your Credit Score Regularly
Keep track of your credit score through reliable platforms. Awareness of your credit standing can help you make informed borrowing decisions and improve your financial health.
🔄 Be Cautious with Buy Now, Pay Later
While Buy Now, Pay Later (BNPL) options can offer convenience, be mindful of the potential for debt. Always read the terms, as missed payments can lead to high fees and affect your credit.
📉 Stay Informed About Consumer Protection
Stay updated on changes within the CFPB. Understanding your rights can help you navigate financial products and services more confidently.
🏆 Consumer Finance Services Ranked by User Reviews (2026)
This section highlights various consumer finance services relevant to personal finance, including credit cards, loans, and investment options. The rankings are based on Trustpilot data checked in October 2026. Note that scores can change over time, and unhappy customers often leave more reviews, which can impact overall ratings.
🥇 1. SoFi
SoFi holds a Trustpilot score of 4.4. The company is known for services like student loan refinancing, personal loans, and mortgage loans. Reviewers mention their user-friendly platform but note delays in customer support responses as a potential drawback.
🥈 2. Robinhood
Robinhood has a Trustpilot score of 3.9. This service is recognized for stock trading, cryptocurrency trading, and cash management. While it provides a convenient platform for investors, some users report issues with customer service and account verification.
🥉 3. Experian
Experian has been rated 4.1. It is best known for credit reporting and monitoring, as well as identity theft protection. Reviewers appreciate the comprehensive services but express concerns about customer service responsiveness.
4️⃣ Credit.com
Credit.com scores 1.7. It offers credit score monitoring and advice. Many reviewers report negative experiences, particularly regarding billing practices, which may deter potential users.
5️⃣ CreditRepair.com
CreditRepair.com holds a low score of 1.2. It provides credit repair services aimed at improving credit scores. However, numerous users have shared negative experiences, particularly with customer service and billing issues.
6️⃣ Prosper
Prosper has a Trustpilot score of 4.5. It specializes in peer-to-peer lending and personal loans. Reviewers appreciate the platform's ease of use, but some have reported customer service responsiveness as an area for improvement.
🆓 Free Consumer Financial Protection Resources
The Consumer Financial Protection Bureau (CFPB) offers various free resources for consumers navigating financial products. These include guides on credit cards, mortgages, and personal finance management, helping individuals understand their rights and options.
🔎 Factors to Compare When Choosing Financial Services
- 📊 Customer reviews and ratings.
- 🏦 Range of financial products offered.
- 📞 Availability and quality of customer support.
- 💰 Fees and interest rates associated with services.
- 🔒 Security measures and data protection policies.
❓ Frequently Asked Questions
❓ What is the current state of credit card debt?
Credit card debt in the U.S. reached $1.25 trillion in early 2026, reflecting a nearly 6% increase from the previous year.
💳 How high are credit card interest rates now?
The average APR for general-purpose credit cards is 25.2%, while private-label cards average 31.3% as of early 2026.
🏠 What are the current mortgage rates?
In the fourth quarter of 2025, the 30-year fixed mortgage rate declined to the low 6% area, providing some relief for homebuyers.
📄 What is the Open Banking Rule?
The Open Banking Rule, effective January 17, 2025, allows consumers to access their financial data from institutions, promoting transparency and control over their finances.
⚖️ How has the CFPB changed recently?
The CFPB has undergone significant restructuring since early 2025, including reducing its activities and staff, which may impact consumer protection efforts.
📉 What challenges is the CFPB facing?
The CFPB faces challenges due to the rise of new and complex financial products, making it harder to protect consumers effectively.
⚖️ Recent Court Cases Related to Consumer Finance
Several recent court rulings have addressed issues relevant to consumer finance, highlighting ongoing legal challenges in the sector.
- New York court rules on U.S. Bank Trust foreclosure caseNew York Supreme Court, Nassau County · April 10, 2026
- Florida court affirms ruling in Kernan v. Deutsche Bank caseDistrict Court of Appeal of Florida · August 12, 2022
- Florida Court Affirms Ruling in Slovak v. Deutsche Bank CaseDistrict Court of Appeal of Florida · November 16, 2022
- Court affirms ruling in Read v. Deutsche Bank Trust CompanyDistrict Court of Appeal of Florida · November 16, 2022
For more details, feel free to browse more rulings on the news page.
End of October 2026 Update
Great Depression Explained:
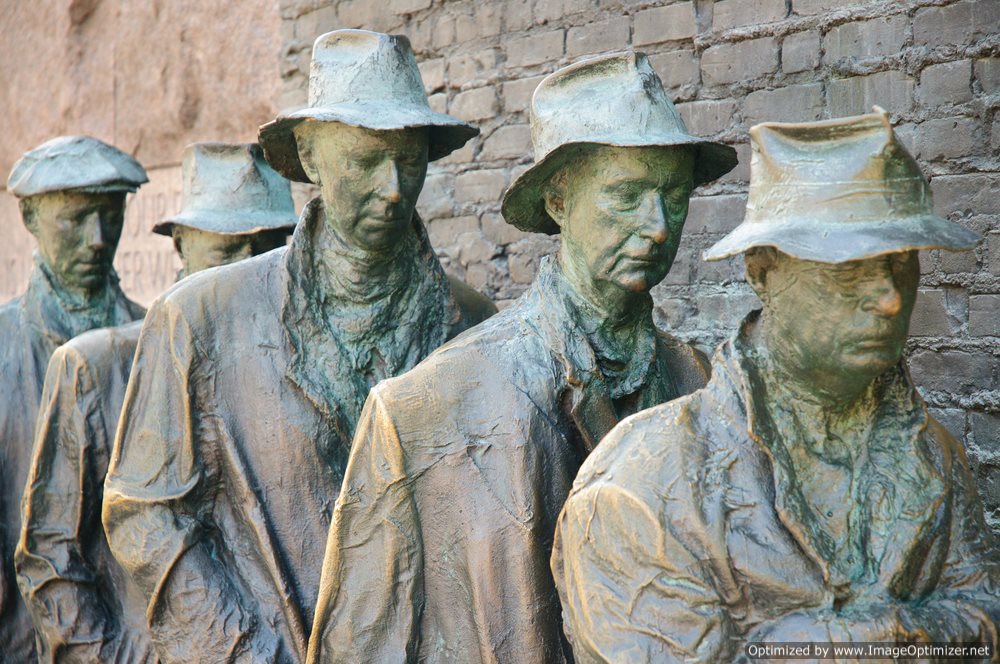
The Great Depression was a disastrous worldwide economic hardship that took place in the decade preceding World War II. The economic impact and the overall timing of such a calamity varied across nations, but in the majority of regions, the Great Depression started in approximately 1929 and lasted until the late 1930s or early 1940s.
How bad was the Great Depression?
The Great Depression was the longest, most widespread and severe economic depression of the 20th century. The economic collapse originated in the United States, starting with a sudden and drastic fall in stock prices that began in September of 1929 and became international news as the entire stock market crashed in October. From there, the Stock Market Crash of 1929 imposed negative externalities and effects on almost every country of the world.
The Great Depression had brutal effects in virtually every region of the world and on nearly every socio-economic class. Personal income, profits, prices and tax revenues dissipated, while international trade plummeted by more than 50%. Unemployment in the United States rose to over 25% and in some nations as high as 33%. Those cities that relied on industry were hit hardest; construction was virtually halted and production was dying as companies failed to raise capital. With plummeting demand and few alternate sources of income, areas dependent on primary sector industries, suffered the most.
How did the Great Depression Start?
The majority of historians and economists agree that the start of the Great Depression was caused by the Stock Market Crash of 1929 and more specifically the precipitous drop in stock market prices that took place on October 29, 1929—a date forever known as Black Tuesday.
The significant loss in the stock market yielded numerous aftereffects that created an avalanche of severe economic problems. By the mid-1930s, interest rates were extremely low, as consumers were reluctant to borrow after losing so much in the market. The losses of money in the market lead to a halt in consumer spending and borrowing. The lack of consumption necessitated a huge pull-back production, which in turn, led to rising unemployment and the deterioration of corporate revenue.
There were multiple causes for the stock market crash of 1929, including the structural weakness and the domino-like effect of falling stock prices. In theory, a great debate centers around the primary cause of the Great Depression and more specifically the stock market crash of 1929. The question, in its rawest form, revolves around whether the stock market crashed because of a failure on the part of the free market or alternatively, a failure of government regulation regarding interest rates, curtailing bank failures and responsibly controlling the money supply.
Two Principal Theories:
Modern theories of the Stock Market Crash 1929 are broadly classified into two main points of view. First, there is the demand-drive theory, which includes under-consumption, malfeasance by bankers and industrialists, the breakdown of international trade and poor government policy. The consensus around this theory is that a large-scale loss of confidence sparked a precipitous reduction in consumption and investment spending. Once deflation set in, the majority of the public believed that they could avoid further losses by removing their money from the markets or staying away from investment.
The second principal theory comes from those who believe that the Great Depression started as simply a recession, but because of policy mistakes and more specifically the shrinking of the money supply, descended into the Great Depression.